Snowball or avalanche: how to choose
Both methods work the same way each month. You pay the minimum on every debt, then put every extra dollar on one target debt. When the target is paid off, its whole payment moves to the next target, so the amount attacking your debt grows as you go. The only difference is the order.
- Debt snowball pays the smallest balance first. You close accounts quickly, which keeps a lot of people going.
- Debt avalanche pays the highest interest rate first. It always costs the same or less in total interest.
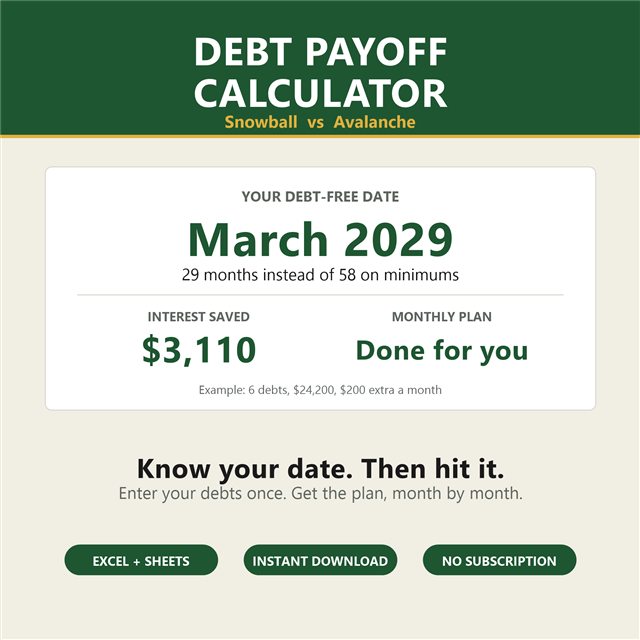
On the sample debts above (six debts, $24,200, $200 extra a month), avalanche costs $3,452 in interest and snowball $3,637. Both finish in 29 months, half the 58 months it takes on minimums alone, which would cost $6,561. If the gap between the two is small for your debts, pick the one you will actually stick with.
Why the extra payment matters more than the method
The biggest difference is not snowball versus avalanche. It is paying a fixed total every month and letting paid-off minimums roll forward, instead of letting each payment shrink as the balance falls. Try changing the extra payment above: the date moves far more than switching methods does.
Check your minimums
If a minimum payment is lower than the interest charged each month, that debt never goes down on minimums alone. The calculator shows "30+ years" in that case. Raise that payment, or put that debt first.
Frequently asked questions
What is the difference between debt snowball and debt avalanche?
Both pay minimums on every debt and send all extra money to one target. Snowball targets the smallest balance; avalanche targets the highest interest rate. Paid-off payments roll into the next target.
Which saves more money?
Avalanche always costs the same or less interest. Snowball usually clears your first debt sooner. On typical debts the gap is often a few hundred dollars.
Is this calculator accurate?
It calculates interest monthly as balance × APR ÷ 12. Lenders that compound daily or charge fees can differ by a few dollars. It is a planning tool, not financial advice.
Sample debts are examples. Replace them with your own balances, rates and minimums. Nothing you enter leaves your browser.